Refereed Publications
[25] Quantile-based Interpretable Neural Network Models: Mortality Forecasting and Actuarial Simulations
Insurance: Mathematics and Economics, forthcoming
Interpretable neural networks estimate mortality quantiles while retaining the structure of classic stochastic mortality models. The framework supports stochastic mortality simulation and longevity-linked derivative pricing.
- Mortality, Health & Longevity
- AI & Machine Learning in Insurance and Finance
[24] Air Quality, Health, and Economic Effects of Land Use and Land Cover changes in Southeast Asia in the 21st Century: A Modelling Study
Lancet Planetary Health, 10(4): 101457
This modelling study connects land-use and land-cover changes in Southeast Asia with air pollution, health outcomes and economic costs. It estimates excess deaths and associated losses through both biogeophysical and biogeochemical pathways.
- Mortality, Health & Longevity
- Climate Risk, Agriculture & Sustainability
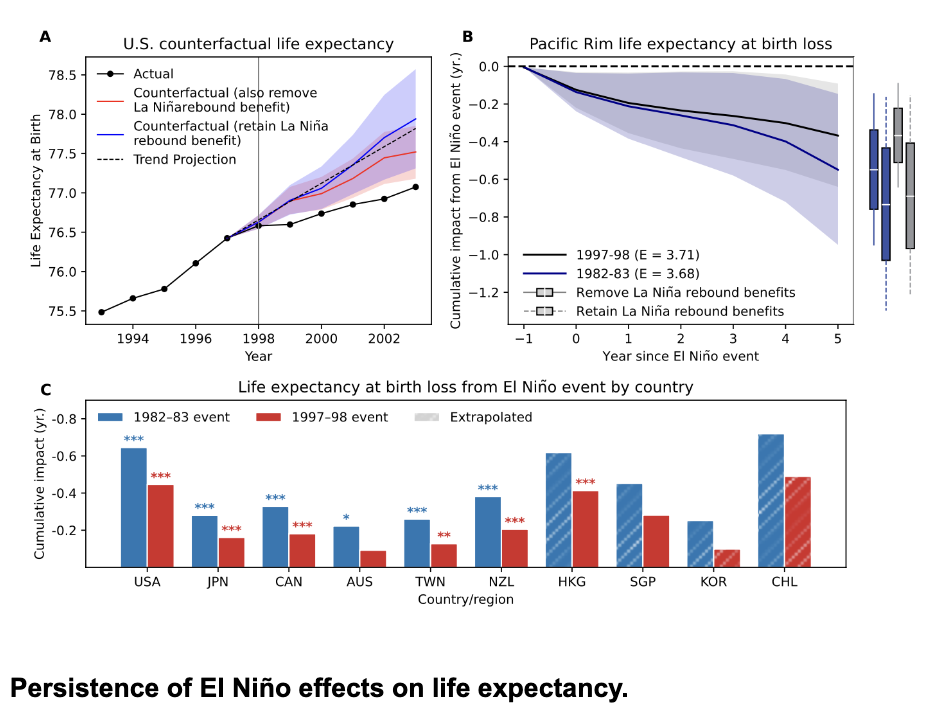
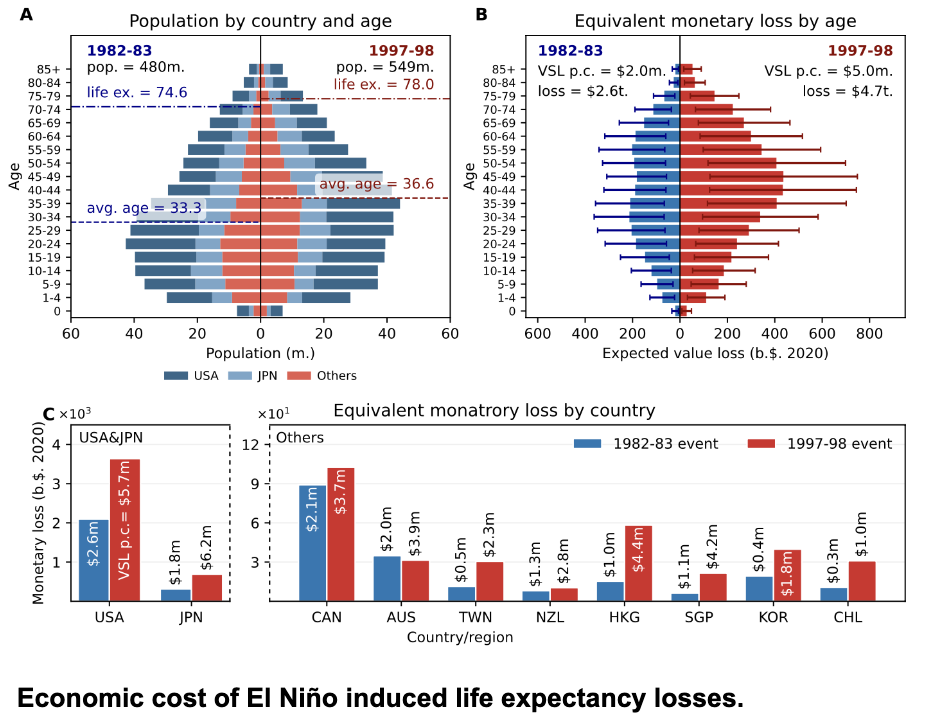
[23] Enduring Impacts of El Niño on Life Expectancy in Past and Future Climates
Nature Climate Change, 16, 148-154
The study quantifies persistent life-expectancy losses from El Niño across high-income Pacific Rim countries, estimating monetary-equivalent losses of US$2.6 trillion and US$4.7 trillion for the 1982–83 and 1997–98 events. Under moderate emissions pathways, projected losses reach US$35 trillion by 2100.
- Mortality, Health & Longevity
- Climate Risk, Agriculture & Sustainability
[22] Index-based Insurance Design for Climate and Weather Risk Management: A Review
in Springer Actuarial, Quantitative Risk Management and Insurance in Agricultural Business, edited by A. Hirbod, P. Liu and S. Wang
This chapter reviews the actuarial foundations, empirical evidence and practical design of index insurance for climate and weather risks. It also discusses potential applications of artificial intelligence and blockchain.
- Climate Risk, Agriculture & Sustainability
- Financial Markets, Hedging & Risk Transfer
[21] Modeling Mortality with Kernel Principal Component Analysis (KPCA) Method
Annals of Actuarial Science, 18(3):626-643
A kernel principal component extension of the Lee–Carter model captures nonlinear patterns in mortality data. Empirical tests examine forecasting performance and uncertainty, including during the COVID-19 pandemic.
- Mortality, Health & Longevity
- AI & Machine Learning in Insurance and Finance
[20] Epidemic Financing Facilities: Pandemic Bonds and Endemic Swaps
North American Actuarial Journal, 28(3):626-657
The paper develops pandemic bonds and endemic swaps to finance severe pandemic outbreaks and recurrent epidemics. Coronavirus and dengue examples illustrate pricing with epidemiological and actuarial models.
- Mortality, Health & Longevity
- Financial Markets, Hedging & Risk Transfer
[19] Digital Financial Inclusion and Tourism Demand: A Spatial Spillover Perspective
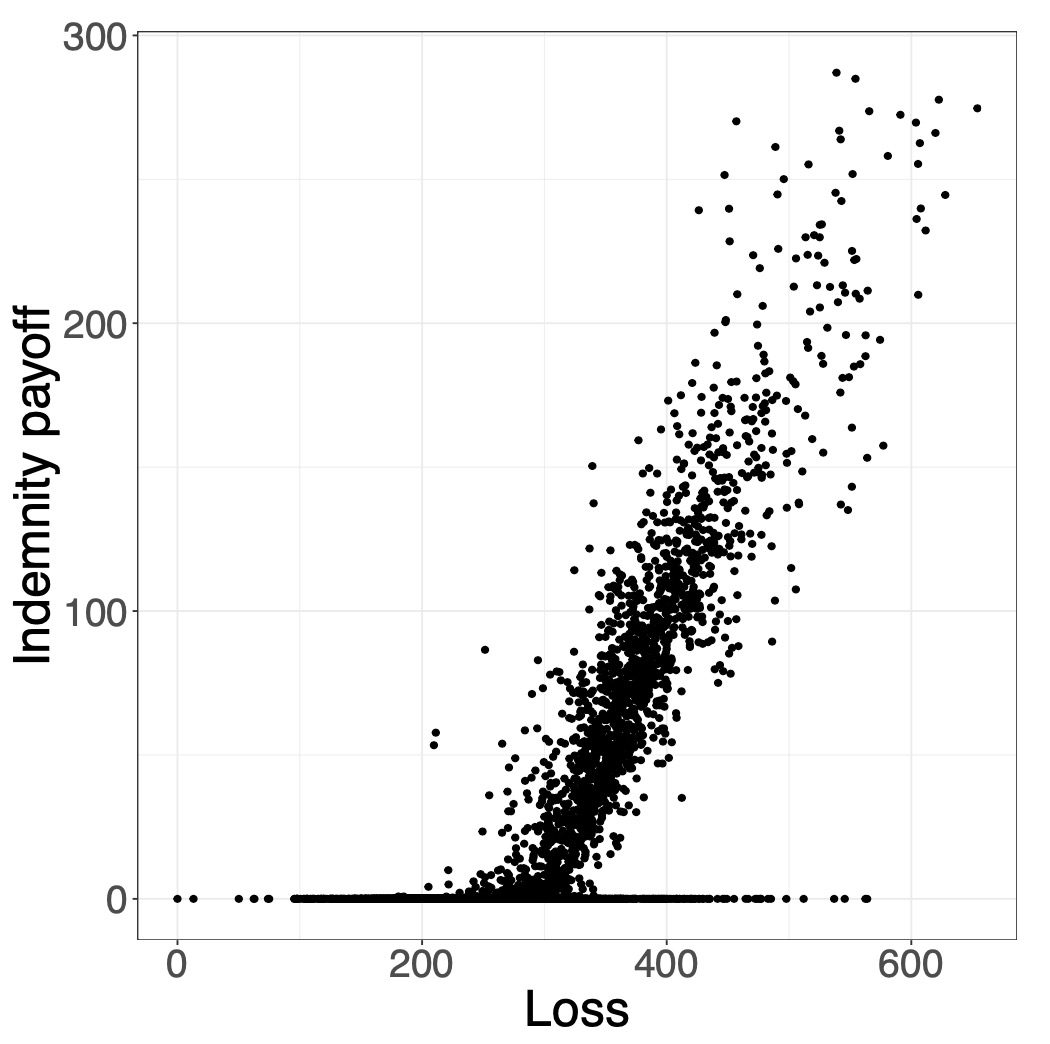
[18] Managing Weather Risk with a Neural Network-Based Index Insurance
Management Science, 70(7):4306-4327
A neural network embedded in a utility-maximization framework designs weather index insurance and endogenously determines premiums and demand. The approach captures nonlinear weather–loss relationships to reduce basis risk and improve welfare.
- Climate Risk, Agriculture & Sustainability
- AI & Machine Learning in Insurance and Finance
- Financial Markets, Hedging & Risk Transfer
[17] Machine Learning in Long-term Mortality Forecasting
The Geneva Papers on Risk and Insurance - Issues and Practice, 49:340-362
This mortality forecasting framework combines neighbouring prediction, model ensembling and tree boosting. Tests using the Human Mortality Database examine long-horizon prediction and the benefits of pooling information across populations.
- Mortality, Health & Longevity
- AI & Machine Learning in Insurance and Finance
[16] Cyber Risk Modeling: A Discrete Multivariate Count Process Approach
Scandinavian Actuarial Journal, 2024(6), 625-655
A count-based frequency–severity framework models cyber events and data breaches, accounting for dependence, zero inflation and heavy tails. The estimation approach is applied to the Privacy Rights Clearinghouse dataset.
- Financial Markets, Hedging & Risk Transfer
[15] Storm CAT Bond: Modeling and Valuation
North American Actuarial Journal. 28(4): 718-743
The paper models and prices storm catastrophe bonds using loss distributions and spatial–temporal dependence. Florida county-level data illustrate how the proposed bonds can hedge reinsurers’ storm losses.
- Climate Risk, Agriculture & Sustainability
- Financial Markets, Hedging & Risk Transfer
[14] A Deep Factor Model for Crop Yield Forecasting and Insurance Ratemaking
North American Actuarial Journal. 28(1): 57-72
A deep factor model combines an autoencoder and convolutional neural networks to forecast crop yields. An application to Iowa data evaluates forecasting accuracy and implications for crop insurance ratemaking.
- Climate Risk, Agriculture & Sustainability
- AI & Machine Learning in Insurance and Finance
[13] Neighbouring Prediction for Mortality
ASTIN Bulletin, the Journal of the IAA, 51(3), 689-718
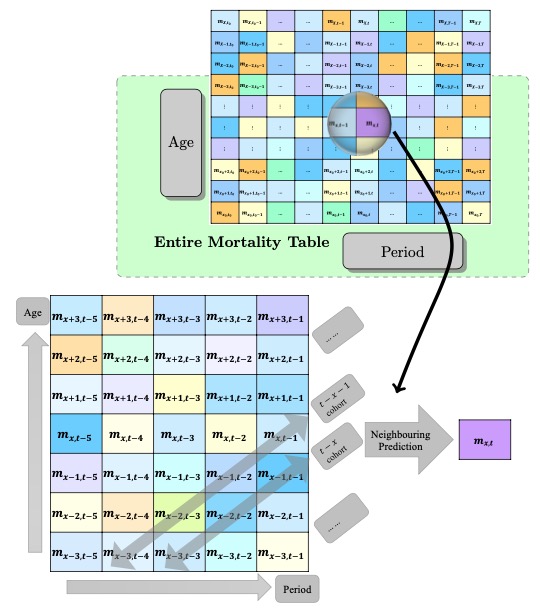
A neighbouring prediction framework treats mortality tables as two-dimensional images, enabling convolutional neural networks to learn intricate nonlinear patterns across ages and years. Evaluations cover 41 countries and regions, with an extension to multiple populations.
- Mortality, Health & Longevity
- AI & Machine Learning in Insurance and Finance
[12] Gompertz Law Revisited: Forecasting Mortality with a Multi-factor Exponential Model
Insurance: Mathematics and Economics, 99, 268-281
A multi-factor exponential extension of Gompertz mortality modelling accommodates flexible age patterns, including at very old ages. The study evaluates historical fit, forecasting and a multi-population extension.
- Mortality, Health & Longevity
[11] Improved Index Insurance Design and Yield Estimation using a Dynamic Factor Forecasting Approach
Insurance: Mathematics and Economics, 96, 208-221
A dynamic factor model summarizes many explanatory variables to forecast crop yields and design weather index insurance. Illinois crop data are used to assess prediction accuracy, basis risk and hedge effectiveness.
- Climate Risk, Agriculture & Sustainability
[10] Dynamic Bayesian Ratemaking: A Markov Chain Approximation Approach
North American Actuarial Journal, 25(2), 186-205
A hidden Markov chain approximation makes Bayesian premiums tractable in insurance models with dynamic unobserved policyholder risk. Numerical and real-data examples evaluate its accuracy and pricing flexibility.
- Financial Markets, Hedging & Risk Transfer
[9] The Design of Weather Index Insurance Using Principal Component Regression and Partial Lease Squares Regression: The Case of Forage Crops
North American Actuarial Journal, 24(3), 355-369
The study compares principal component regression and partial least squares regression for constructing multivariable weather insurance indices. Ontario forage data illustrate how dimension reduction can address multicollinearity and basis risk.
- Climate Risk, Agriculture & Sustainability
[8] Remote Sensing Applications for Insurance: An Example of Predicting Forage Crop Loss in the Presence of Systemic Weather Risk
North American Actuarial Journal, 24(2), 333-354
The paper compares thirteen pasture production indices, including satellite-derived vegetation and biophysical measures, for predicting forage losses. Alberta pasture observations provide a validation testbed for remote-sensing applications in insurance.
- Climate Risk, Agriculture & Sustainability
[7] A Relational Data-Matching Model for Enhancing Individual Loss Experience: An Example from Crop Insurance
North American Actuarial Journal, 23(4), 551-572
A relational data-matching model borrows loss experience from similar regions when farm-level yield data are unavailable. Canadian and U.S. corn data are used to assess yield predictions and premium-rate estimates.
- Climate Risk, Agriculture & Sustainability
[6] Agricultural Insurance Ratemaking: Development of a New Premium Principle
North American Actuarial Journal, 23(4), 512-534
A multivariate weighted premium principle reweights historical agricultural losses using external risk information. Manitoba reinsurance data illustrate its pricing implications and allocation of loadings across risk layers.
- Climate Risk, Agriculture & Sustainability
[5] A Credibility-based Yield Forecasting Model for Crop Reinsurance Pricing and Weather Risk Management
Agricultural Finance Review, 79(1), 2-26
A credibility-based crop yield model combines weather information and production data across geographically correlated regions. The resulting framework supports reinsurance pricing and weather risk management.
- Climate Risk, Agriculture & Sustainability
[4] Spatial Dependence and Aggregation in Hedging Systemic Weather Risk: A Lévy Subordinated Hierarchical Archimedean Copulas (LSHAC) Approach
ASTIN Bulletin, the Journal of the IAA, 48 (2), 779-815
A Lévy subordinated hierarchical Archimedean copula (LSHAC) model captures spatial dependence in weather risks to support agricultural hedging. The analysis examines basis risk, downside protection and the effects of spatial aggregation.
- Climate Risk, Agriculture & Sustainability
- Financial Markets, Hedging & Risk Transfer
[3] Modeling Multi-population Longevity Risk with Mortality Dependence: A Lévy Subordinated Hierarchical Archimedean Copulas (LSHAC) Approach
Journal of Risk and Insurance, 84, 477-493
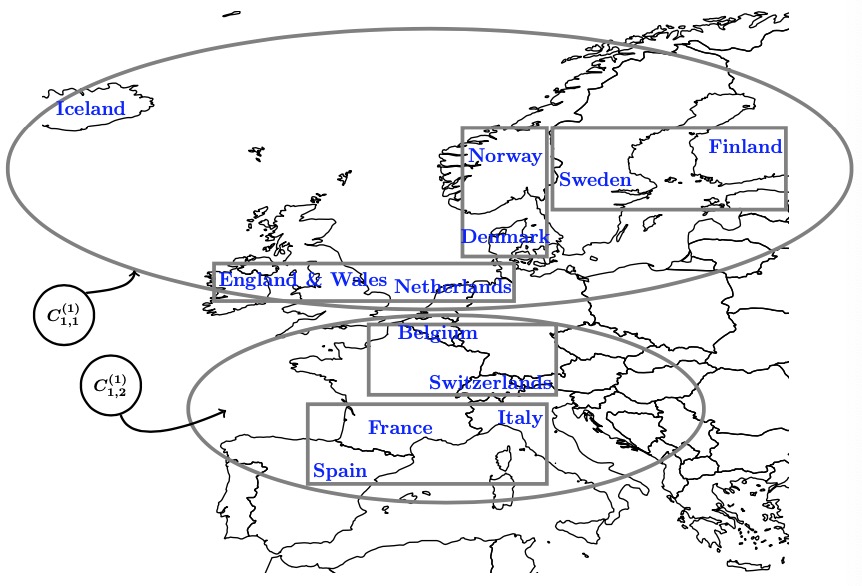
A Lévy subordinated hierarchical Archimedean copula (LSHAC) framework models mortality dependence across countries and is evaluated using data from thirteen countries. A survival index swap example illustrates the role of dependence in longevity risk and population basis risk.
- Mortality, Health & Longevity
- Financial Markets, Hedging & Risk Transfer
[2] Structure and Estimation of Lévy Subordinated Hierarchical Archimedean Copulas (LSHAC): Theory and Empirical Tests
Journal of Banking & Finance, 69, 20-36
The paper develops the theory and estimation procedure for Lévy subordinated hierarchical Archimedean copula (LSHAC) models. Exchange-traded fund data illustrate applications to tail dependence and Value-at-Risk estimation.
- Financial Markets, Hedging & Risk Transfer
[1] A credibility-based Erlang mixture model for pricing crop reinsurance
Other Publications (e.g., Technical Reports, etc.)
[13] Cyclones in the Asia Pacific: A View to Future Risks
Global Asia Insurance Partnership (GAIP) Living Lab Report. June 2026
A technical report on cyclone risk in the Asia Pacific and its future outlook.
- Climate Risk, Agriculture & Sustainability
[12] Climate-Adjusted Mortality Modelling in Asia
Global Asia Insurance Partnership (GAIP) Living Lab Report. March 2026
The report proposes a Climate Risk Adjustment Factor (CRAF) to incorporate climate effects into mortality tables, supporting insurers’ climate stress testing and forward-looking risk assessment in Asia.
- Mortality, Health & Longevity
- Climate Risk, Agriculture & Sustainability
[11] Climate Anomalies’ Enduring Impacts on U.S. Mortality and Health Landscape
Society of Actuaries Research Institute
A technical report on the lasting effects of climate anomalies on mortality and health in the United States.
- Mortality, Health & Longevity
- Climate Risk, Agriculture & Sustainability
[10] Inland Flood Risk Modeling in Southeast Asia
Global Asia Insurance Partnership (GAIP) Living Lab Report. May 2025
A technical report on modelling inland flood risk in Southeast Asia.
- Climate Risk, Agriculture & Sustainability
[9] The Economics of El Niño: A look at climate challenges in Southeast Asia
The Actuary Magazine
A magazine article discussing El Niño and climate-related economic challenges in Southeast Asia.
- Climate Risk, Agriculture & Sustainability
[8] Sea level rise: Importance to the insurance sector
A technical report discussing the relevance of sea-level rise to the insurance sector.
- Climate Risk, Agriculture & Sustainability
[7] Record-breaking El Nino could hurt South-east Asia’s growth
Business Times, 22 Sep 2023, Page 16
A newspaper article discussing how a record-breaking El Niño could affect economic growth in Southeast Asia.
- Climate Risk, Agriculture & Sustainability
[6] Reply to Hans U. Gerber and Elias SW Shiu on Their Discussion on Our Paper Entitled Agricultural Insurance Ratemaking: Development of a New Premium Principle
North American Actuarial Journal 25 (3), 466-467
A response to Gerber and Shiu’s discussion of the proposed premium principle for agricultural insurance.
- Climate Risk, Agriculture & Sustainability
[5] Reply to Abylay Zhexembay on the Discussion on Our Paper Entitled Agricultural Insurance Ratemaking: Development of a New Premium Principle
North American Actuarial Journal 25 (3), 472-472
A response to Abylay Zhexembay’s discussion of the proposed premium principle for agricultural insurance.
- Climate Risk, Agriculture & Sustainability
[4] Predictive Analysis: The Effects of Technology and Weather on Crop Yield
Society of Actuaries Research Report, December, 2019
A technical report on predictive analysis of technology, weather and crop yields.
- Climate Risk, Agriculture & Sustainability
[3] Assessing the Feasibility and Development of a Forage Insurance Plan using Satellite-Derived Biophysical Parameters with a Focus on the Province of Alberta, Canada
A technical report assessing forage insurance based on satellite-derived biophysical parameters in Alberta, Canada.
- Climate Risk, Agriculture & Sustainability
[2] Assessing the Feasibility and Development of a Forage Insurance Plan using Satellite-Derived Biophysical Parameters with a Focus on the Province of Saskatchewan, Canada
A technical report assessing forage insurance based on satellite-derived biophysical parameters in Saskatchewan, Canada.
- Climate Risk, Agriculture & Sustainability
[1] Farm-Level Crop Yield Forecasting in the Absence of Farm-Level Data
Society of Actuaries Research Report, October, 2016
A technical report on forecasting farm-level crop yields when farm-level data are unavailable.
- Climate Risk, Agriculture & Sustainability
No publications match this search. Try another term or reset the filters.
Note: * denotes graduate students; ** denotes research fellows.