Journal article
Journal of Risk and Insurance · 2017-04 · Volume 84 · Issue S1 · pp. 477-493
DOI: 10.1111/jori.12198
Published online: 2017-02-09 · Download citation (BibTeX)
Abstract
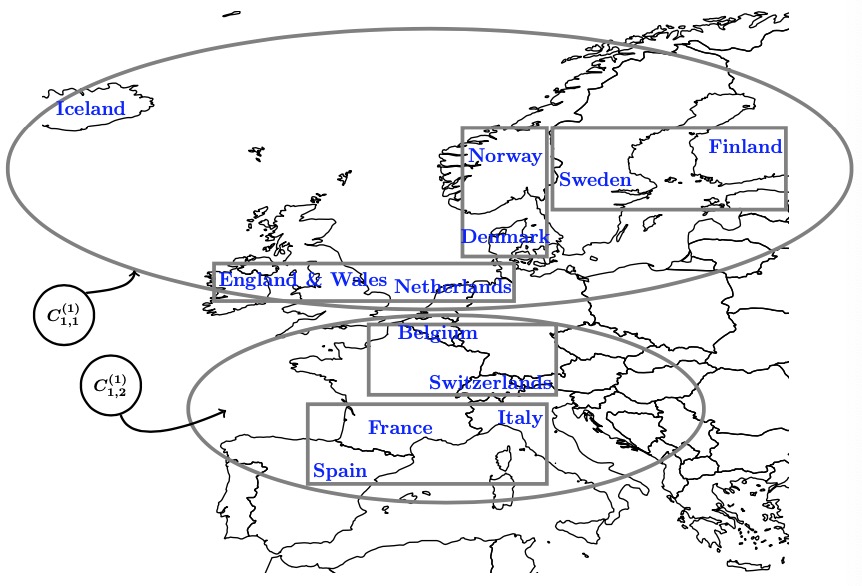
This paper proposes a new copula model known as the Lévy subordinated hierarchical Archimedean copulas (LSHAC) for multi-country mortality dependence modeling. To the best of our knowledge, this is the first paper to apply the LSHAC model to mortality studies. Through an extensive empirical analysis on modelling mortality experiences of 13 countries, we demonstrate that the LSHAC model comparing to the elliptical copulas. In addition, the proposed LSHAC model generates out-of-sample forecasts with smaller standard deviations, when compared to other benchmark copula models. The LSHAC model also confirms that there is an association between geographical locations and dependence of the overall mortality improvement. Finally, the model is used to price a hypothetical survival index swap written on a weighted mortality index. The results highlight the importance of dependence modeling in managing longevity risk and reducing population basis risk.
Keywords: Geographical Mortality Dependence; Longevity Securitization; Hierarchical Archimedean copulas; Lévy subordinators
Related material
Illustrative Grouping Results of 13 Countries.