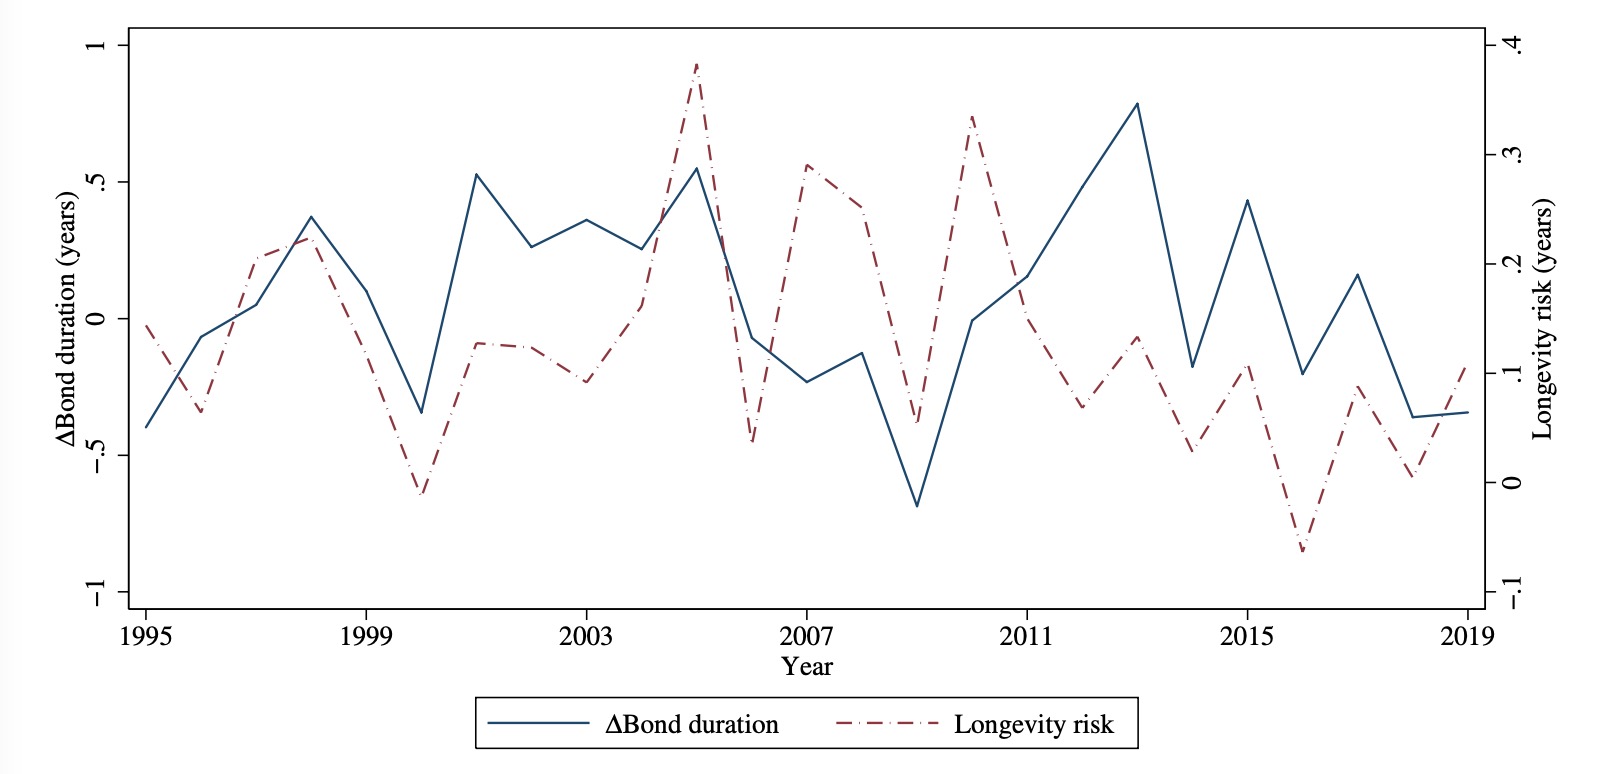
Intermediary Demand for Duration and Corporate Financing: Evidence from Longevity Shocks
Robust Testing in High-Dimensional Linear Model
Working Paper
The paper develops joint significance tests for high-dimensional linear regression with heteroskedastic and dependent errors. Random matrix theory and self-normalization provide inference without requiring a known sparsity level or error-dependence structure.
- Financial Markets, Hedging & Risk Transfer
Arbitrage-Free Pricing of Reverse Mortgages using Neural Stochastic Differential Equations
Working Paper
A neural stochastic differential equation framework jointly models mortality, interest rates and housing conditions for reverse mortgage valuation. Forecasting and simulation results inform a Monte Carlo pricing engine for tenure-payment contracts.
- Mortality, Health & Longevity
- AI & Machine Learning in Insurance and Finance
- Financial Markets, Hedging & Risk Transfer
Sustainable Area-Yield Insurance Program with Optimal Risk Pooling: A Behavior-Based Machine Learning Approach
A behaviour-based machine learning framework forms risk pools for area-yield insurance using utility maximization and spectral clustering. U.S. corn and soybean data are used to evaluate basis risk, tail risk and contract performance.
- Climate Risk, Agriculture & Sustainability
- AI & Machine Learning in Insurance and Finance
A Geo-Hierarchical Deep Learning Approach for Flood Insurance Modeling and Pricing
(Previously titled "Borrowing Information Across Space and Time: Pricing Flood Risk with Physics-based Hierarchical Machine Learning Models")
A geographically structured deep learning model captures spatial dependencies in flood hazards to inform insurance pricing. Mississippi River Basin data and an application to the National Flood Insurance Program are used to evaluate hazard estimates, premiums and capital requirements.
- Climate Risk, Agriculture & Sustainability
- AI & Machine Learning in Insurance and Finance
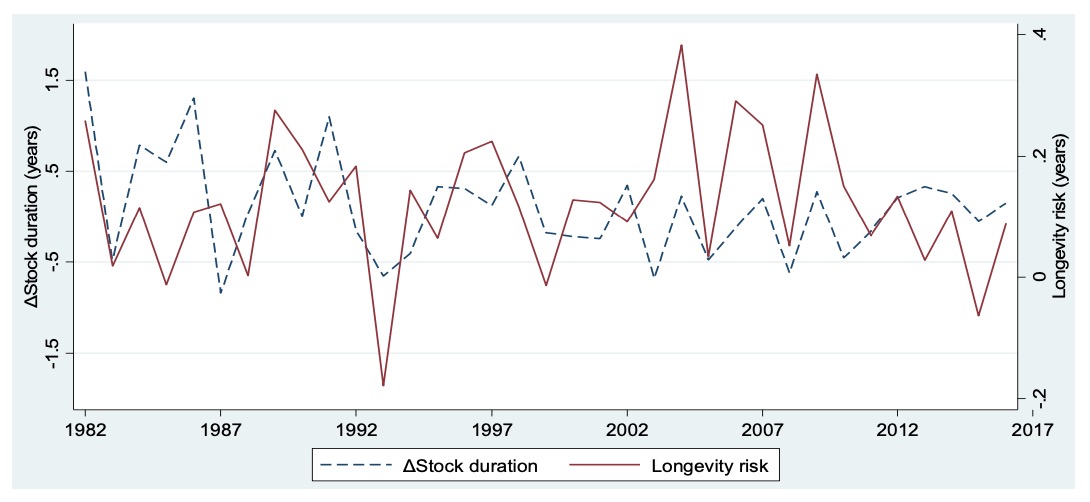
Duration-Hedging Trades, Return Momentum and Reversal
No working papers match this search. Try another term or reset the filters.
Note: * denotes graduate students; ** denotes research fellows.