Working paper
Working paper · 2021
(Previously titled "Debt Market Responses to Longevity Shocks")
Abstract
Life insurers manage long-duration liabilities and are major investors in corporate bond markets. We study whether changes in insurers' demand for duration affect corporate financing. Using annual revisions in life expectancy, we show that improvements in longevity increase the duration of insurers' corporate bond portfolios. The response is strongest among insurers with greater exposure to longevity-sensitive liabilities and is supported by evidence from local longevity shocks, opioid-related mortality, and within-bond trading patterns. Positive longevity shocks are associated with lower corporate term spreads and longer debt maturity among firms with greater exposure to insurer demand. The results suggest that demographic shocks affect corporate financing through intermediary demand for duration in corporate bond markets.
Related material
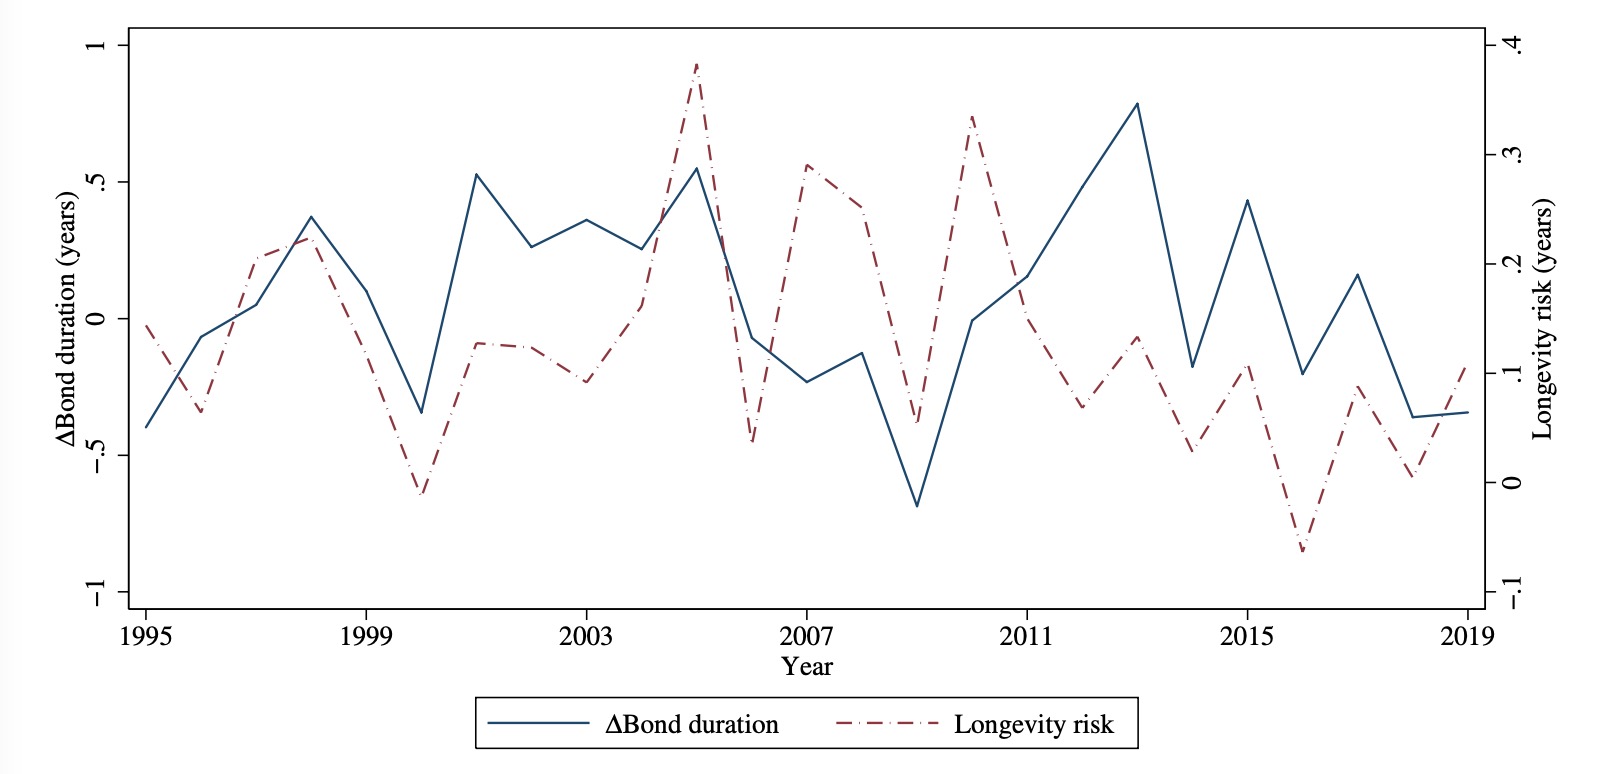
Changes in bond duration of life insurers and longevity risk. The blue solid line shows changes in average duration of life insurers’ bond holdings, while the red dashed line indicates longevity risk.