Working paper
Working paper · 2021
Abstract
We study the duration-hedging trades of duration-sensitive strategic investors, i.e., pensions and life insurers. We use longevity shocks to identify their duration-hedging trades. Longevity shocks affect these investors’ liability duration and induce them to adjust their asset duration. When longevity shocks are low (high), they buy more short- (long-) duration stocks and sell more long- (short-) duration stocks. Because prior winners (losers) have shorter (longer) duration, they behave like momentum (con- trarian) traders when longevity shocks are low (high). We further verify this channel using capital flows and cross-state longevity variations.
Related material
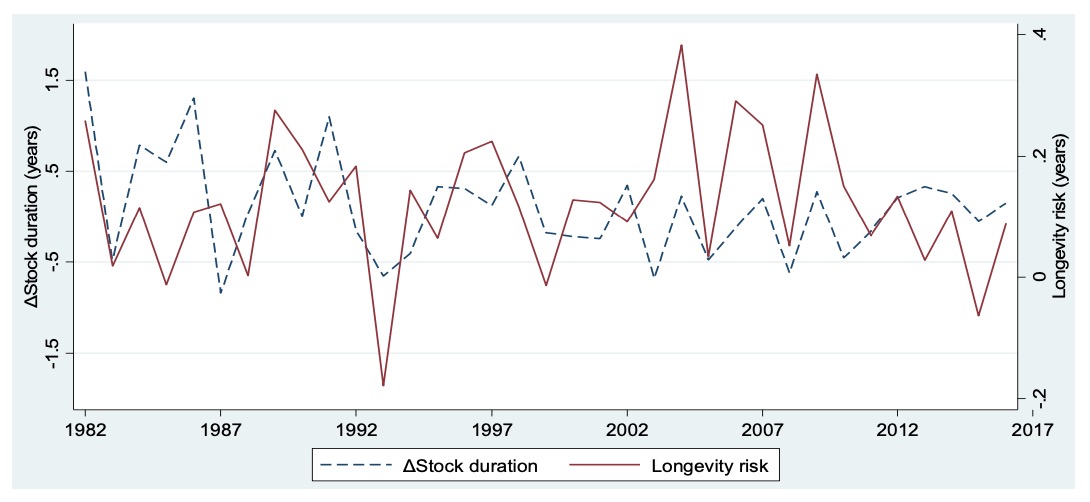
Changes in stock duration of pensions and longevity risk. This plot shows the changes in duration of pensions' stock holdings (the blue dashed line), together with longevity risk (the red solid line).